Reading the table
How to use this directory
Screen restaurant franchise packets by format and capital, then read the FDD, then talk to franchisees. Unit count is history; format and contract are the screen.
Compiled from public filings and operator sites
You do not pick a winner from a cuisine. You narrow a pile of packets until the remaining ones match the capital, labor, site and risk you can actually carry, then you read the disclosure and talk to operators who have already signed. This directory is built for that first cut. The FDD, the franchise agreement, and the calls still have to happen.
Qualify the person, screen brands by format and money, then sit with the document, then call operators. This directory does not place buyers, take a brand’s fee, or rank offerings for sale. It publishes dated fields from Franchise Disclosure Documents and a May 2024 comparative study of published FDDs so the screen can be done on the same numbers every time.
The method chapters live on QSR Field Guide. The Item 7 line-item grouping lives on the Buildout Index. This page is the reading order that ties those publications to the tables here.
Qualify the buyer before opening the table
A standing-service counter, a platter shop, a 2,000-square-foot grill, a drive-through, a host-location taco counter and a teppan dining room are different businesses even when they all fit under “quick service.” Cash available for a first unit has to include working capital, without treating the low end of any Item 7 as a bid. Who will be in the store — the buyer, a hired manager, or a multi-unit schedule — changes which rows survive.
Only then open the main fee table. Fourteen filings sit on it and thirteen are ranked by the disclosed ongoing-fee stack — royalty plus brand fund plus any required local advertising. bluTaco is unranked because the May 2024 study does not disclose both a royalty and a brand fund. Doner Shack is ranked at 10% from its FDD issued 29 April 2025 and has no US outlets in that document’s Item 20. Those two facts already prevent a sloppy shortlist: a missing percentage is not a bargain, and a complete fee stack is not evidence that anyone has operated the format here.
If the cuisine is already chosen, the category pages are the next stop rather than every row on the homepage. German döner, Mediterranean and halal, chicken, and hot dogs each have an essay and, where a pair exists, a generated compare.
Format, capital, term, Item 19 presence, and the dated Item 20 count are the five filters that belong on the same page as the stack. The low end of Item 7 is not a quote. The high end is the planning stress-test.
Screen by format, then by capital
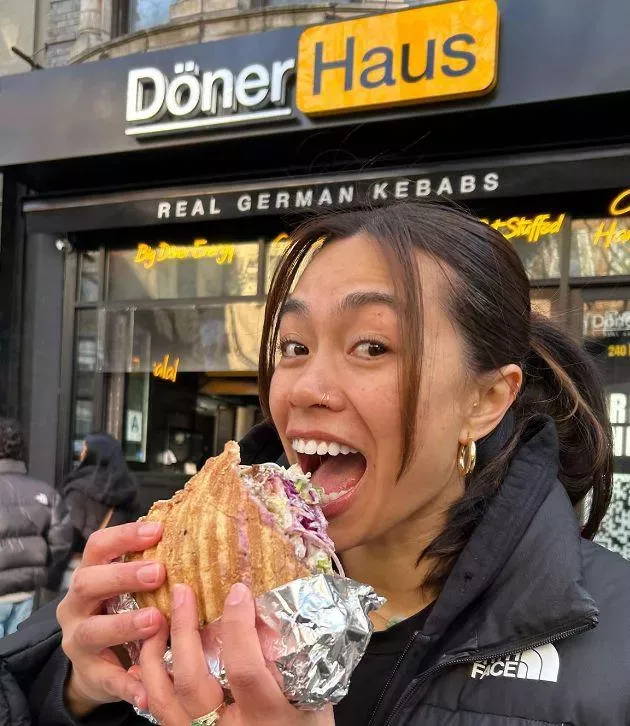
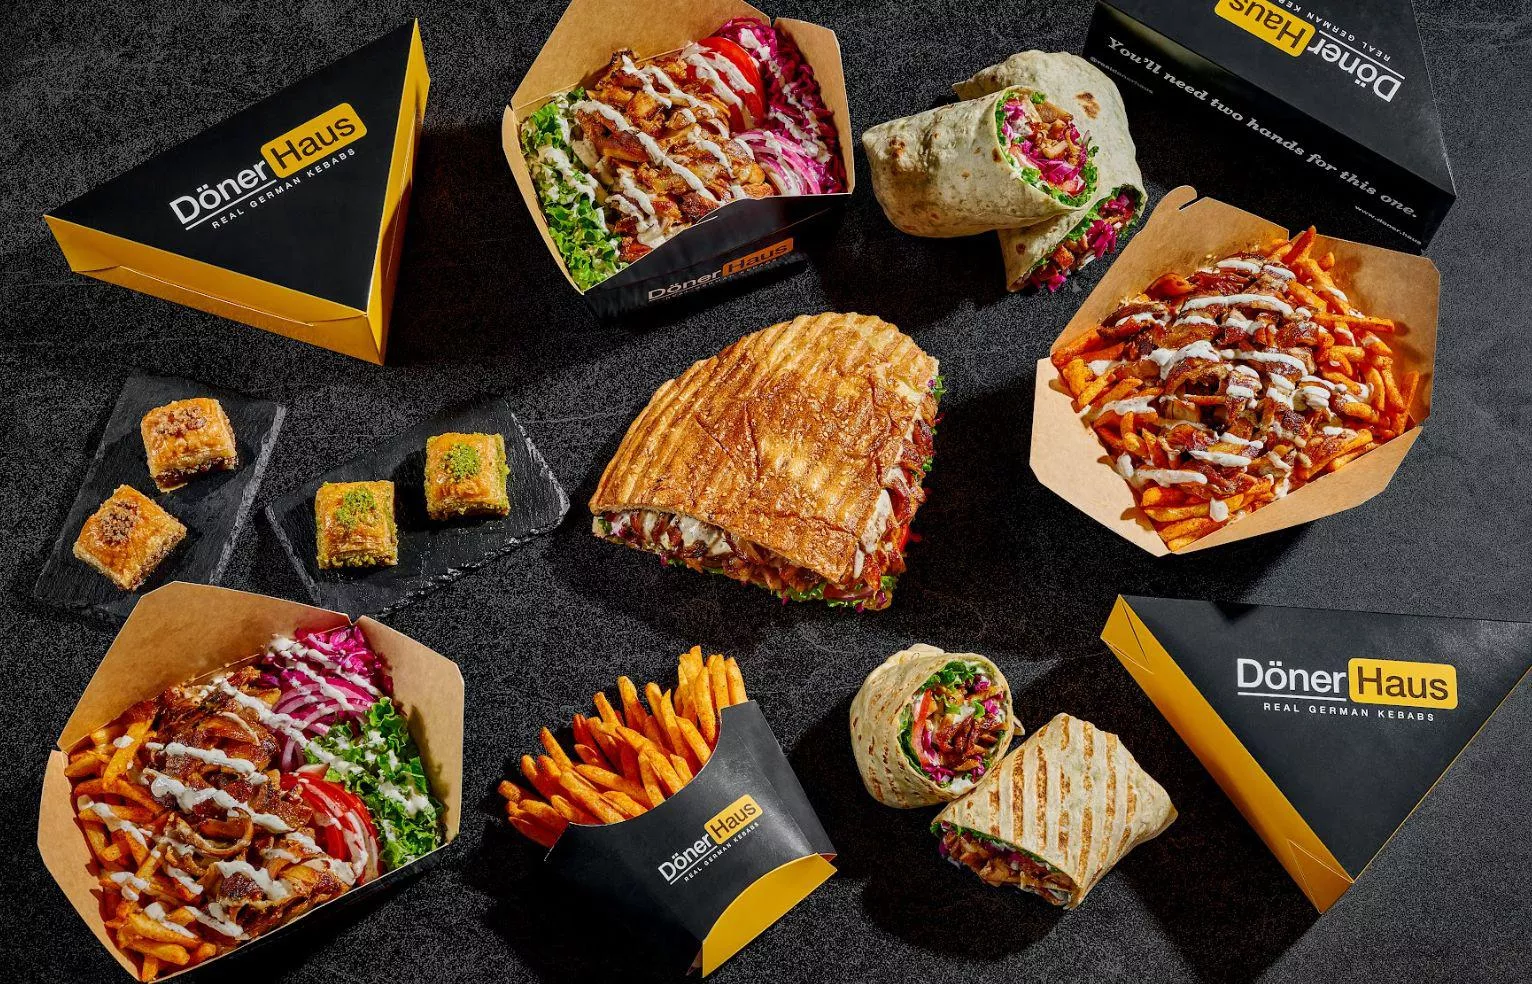
Format is the filter that saves the most time. Döner Haus’s 2026 Franchise Disclosure Document describes an 850–1,200-square-foot standing-service imbiss. German Doner Kebab’s FDD issued 3 September 2024 describes a 1,200–1,400-square-foot restaurant inside a five-outlet minimum. A buyer who can buy one compact shop is not a buyer for GDK’s disclosed development structure. That is the entire point of the Döner Haus versus GDK compare.
Chicken is the same error with different nouns. 375° Chicken ‘n Fries, FDD issued 30 April 2024, covers 800–1,500 square feet and $324,100–$521,500. Mad for Chicken, FDD issued 12 March 2025, covers a 2,000–4,000-square-foot restaurant at $321,125–$691,700 and separately discloses an express range of $243,500–$470,700 and a Multi-Unit Development Agreement at $263,500–$711,700 covering a three-outlet commitment plus the first outlet. Mixing the express low end with the full-restaurant kitchen produces a project no table in that filing describes. Use chicken and fries and the 375° versus Mad for Chicken compare.
Hot dogs split on age, exit rights and missing data. Wienerschnitzel’s May 2024 study row is 323 units, founded 1961, 20-year term, no protected territory, no renewal right and no right to sell. Dog Haus is 58 franchised units, founded 2010, successive ten-year terms, and an Item 7 of $357,437–$625,800. Wienerschnitzel has no Item 7 in the files behind this directory. Filling that blank from a portal leaves the method. See hot dogs and sausage and Dog Haus versus Wienerschnitzel.
Capital is the second filter. Shah’s Halal Food, FDD issued 10 April 2024, prints $197,000–$405,000. Pepper Lunch, May 2024 study, prints $609,200–$1,471,500. Those are not the same cheque. The entry-cost ranking sorts the low end while keeping the high end visible; the high end is the number to underwrite. Great Greek’s low end uses a discounted franchise fee available only to owners of affiliated brands; a first-time buyer pays $39,500, not the discounted figure buried in the $582,014 low total.
| Screen | Use this view | Stop if |
|---|---|---|
| Cuisine aisle | By category | The food is not on the table |
| Box size | By footprint | The disclosed range does not match the site |
| Opening cheque | By investment | The high end exceeds available capital |
| Ongoing load | Fee table | The stack, plus any noted extra fees, is unacceptable |
| Documentation | By Item 19 | The buyer insists on a sample the filing does not make |
| Duration | By term | Renewal or transfer rights contradict the exit plan |
| Age and scale | By age, by size | The buyer wanted a drive-through, a 20-year no-sale contract, or a five-outlet minimum the row does not describe |
Extra fees that sit outside the ranked stack still belong in the screen. Capriotti’s study row adds a 0.65% technology fee. Dog Haus adds a $5,000 annual technology development fee, and its marketing fee may rise to 3.5%. GDK allows annual increases to royalty and brand fund with no cap. Mad for Chicken’s brand fund and media fee can each rise to 2%. The stack is the comparable slice; it is not the entire cash burden.
Read the FDD, then validate
Once two or three packets survive the screen, stop using the directory as evidence. Obtain the current Franchise Disclosure Document. Match the legal franchisor on the cover to the party named in the agreement. Record the issuance date. Then read Items 5, 6 and 7 together, Item 19 with its population, Item 20 with openings and closures, and Items 11, 12 and 17 for training, territory and exit. The field guide’s FDD walkthrough is the seven-move first pass.
Filing years in this directory are not the current offer just because the brand is still selling. Great Greek’s row is the FDD issued 17 August 2023. GDK, Shah’s and 375° are 2024 issued documents. Mad for Chicken and Doner Shack are 2025 documents. Döner Haus is a 2026 row. The May 2024 study supplies Halal Guys, Dog Haus, Crave, Pepper Lunch, Capriotti’s, Wienerschnitzel and bluTaco. Quoting these numbers in a 2026 memo without pulling the current FDD is quoting a snapshot, not the offer.
Validation is Item 20’s current and former franchisee lists, used as a calling list, not a Google review average and not a discovery-day testimonial. For Shah’s, the 2024 filing says no franchises were operating; 44 of 58 outlets were licensed. Those licensees are not a franchisee validation sample for the agreement being offered. For 375°, the 2023 year-end count is five outlets, two of them franchised. The former-franchisee list will be short. For GDK, Item 20 records seven franchised outlets at year-end 2023 while Item 1 of the same 2024 filing said nine were open by issuance. Those are two snapshots in one document. Call the people on the list.
Keep adjacent categories from collapsing
People shopping “kebab” are routinely handed platter brands, Greek grills and chicken-and-rice counters. Those systems compete for similar urban boxes and lunch occasions. Treating them as the same food or the same certification is the error. The Mediterranean and halal essay separates cuisine, audience and religious dietary claims. The German döner essay separates franchise systems from independent shops and company development maps. The döner versus halal essay is the cross-aisle reading, not a winner.
Halal Guys versus Shah’s is a pair inside that aisle: the compare turns on franchised versus licensed footprint and on the absence of Item 19 in both source rows. Great Greek versus Halal Guys, the compare, turns on a 35-year grill versus a cart-origin platter system. Neither pair answers whether the buyer wants pide, gyro or chicken over rice.
Emerging versus established is the last screen people skip. That essay puts Döner Haus’s six shops in three years — seven-plus in construction, 55 commitments, none closed — beside Wienerschnitzel’s 323-unit, 1961 drive-through and GDK’s seven-unit 2023 count with later closures. Unit count is history. Format and contract are the screen.
What the table will not do
It will not score brands. It will not fill a blank from a portal. It will not treat Item 20 as tonight’s locator. It will not convert Item 19 presence into a forecast. It will not read Doner Shack’s disclosed terms as evidence that the brand is recruiting, or the hold notice on its own site as evidence that no current document exists. It will not take a placement fee.
A proper use of this directory produces a short written list: two or three packets, each with format, source year, Item 7 range, fee stack, Item 19 population or explicit absence, Item 20 count and ownership mix, term and territory in the filing’s words, and the next document to request. Everything after that list is the FDD, the accountant, the lawyer and the operators on the Item 20 list. The table is how you get to that list without confusing a compact imbiss with a five-store development deal.